Guide
Commercial Property & "Assured Return" Schemes in NCR: An Honest 2026 Guide
An honest 2026 guide to commercial property in NCR — how 'assured return' schemes really work, why the biggest promises are the biggest risks, how commercial returns actually come, and how to buy shops, offices and studios safely.

Key takeaways
- 'Assured return' is a developer promise to pay a fixed percentage until possession — it is NOT protected by RERA and is only as sound as the developer's cash flow.
- The promised return is usually priced into an inflated purchase cost, and it typically stops at possession — just when leasing risk actually begins.
- A pre-leased or well-located unit at an honest 6–8% from a credible developer is generally safer than a headline 10–15% assured-return pledge.
- Commercial returns really come from footfall, the tenant secured and the exact unit position — selection matters far more than in residential.
- Judge any commercial buy on developer strength, RERA status, location and realistic occupier demand — never on the promised return alone.
Commercial property is sold in the NCR with a promise that sounds almost too good to refuse: buy this shop or office, and the developer will pay you a fixed 10, 12 or even 15 percent every year until possession. Against a fixed deposit or a rental flat yielding 3 percent, that looks irresistible. This guide explains, honestly, how "assured return" schemes actually work, why the biggest promises are usually the biggest risks, how commercial returns really come, and how to buy a shop, office or studio in NCR the safe way. As a RERA-registered channel partner, we would rather you earn a real 7 percent for years than chase a promised 15 percent that quietly disappears.
What an "assured return" scheme actually is
An assured return (sometimes "committed return" or "assured rental") scheme is a promise by the developer to pay the buyer a fixed percentage of the amount invested, usually monthly or quarterly, for a defined period — most often until the project is completed or the occupancy certificate is issued, and occasionally for a year or two beyond. It is most common in commercial products: retail shops, food courts, office suites, shop-cum-office (SCO) units, and studio or serviced-apartment formats near demand catalysts like an airport or an office hub.
The crucial thing to understand is what is doing the paying. The money is not coming from a tenant renting your unit — the unit is usually not even built yet. It is coming from the developer, out of the pool of buyer funds and the developer's own cash flow. In other words, an assured return is a corporate promise from the builder, structured as income to you. That single fact governs everything about its risk.
Why it looks so attractive — and why that is the point
The appeal is obvious: a double-digit "return" that starts immediately, on an asset you also expect to appreciate, beats almost any conventional instrument. Developers use it precisely because it is a powerful sales tool — it lets them raise money from buyers up front, at rates often cheaper than borrowing from a bank, while the scheme's headline number does the marketing.
That framing should make you cautious rather than excited. When a developer is willing to pay you 12–15% a year, ask the obvious question: why would a business pay you that much for your money, when secured commercial borrowing costs it less? The usual answer is that the assured return is not really a return at all — it is a rebate of your own inflated purchase price, paid back to you in instalments. Which brings us to the risks.
The honest risks nobody puts in the brochure
It is not RERA-guaranteed. This is the single most important point. RERA regulates the project's registration, disclosures and timeline, but an assured-return payout is a private commercial promise between you and the developer. If the developer stops paying, RERA does not backstop that income. Your recourse is contractual and slow.
The return is usually priced in. In many schemes the "assured" percentage is simply built into a purchase price set 15–30% above the honest market rate. You are, in effect, being handed back your own overpayment month by month and told it is yield. When the scheme ends, you may be left holding a unit worth less than you paid.
It stops exactly when real risk begins. Most assured returns run only until possession or the occupancy certificate. That is precisely the moment the developer's obligation ends and yours begins — you now own a completed unit that must find a real tenant at a real market rent. If the location has not matured or the project has not leased up, your income can fall off a cliff from 12% to near zero overnight.
It depends entirely on developer solvency. Because the payout comes from the developer's cash flow, an assured return is only as reliable as the developer's finances and its ability to keep selling and building. If cash flow tightens — as it does across cycles, and as the softer NCR sales volumes in recent research suggest can happen — the assured payments are among the first things to stop. The market is full of stalled "assured return" projects where the payments dried up years before possession.
None of this means every scheme is a scam. It means the promised return tells you almost nothing about whether the investment is sound, and the higher the promise, the harder you should look at what is really being sold.
A worked example of how the maths often works
Consider a shop marketed at ₹1 crore with a "12% assured return till possession, three years away." That sounds like ₹12 lakh a year, ₹36 lakh over three years. Now look underneath. Suppose the honest market price for that unit is really ₹78–80 lakh, and the extra ₹20–22 lakh is the developer's cushion. Over three years the developer pays you ₹36 lakh — but a large part of that is simply your own inflated payment returned to you, and all of it is money you handed over up front. At possession, the assured payments stop, and the unit now has to earn its keep from an actual tenant. If a real tenant will pay, say, ₹40,000 a month, that is ₹4.8 lakh a year — roughly a 6% yield on the honest ₹80 lakh value, or under 5% on the ₹1 crore you actually paid. The headline was 12%; the durable reality is closer to 5–6%, on an asset you may have overpaid for. This is not a hypothetical trap; it is the standard shape of many schemes. The lesson is simple: always work out what the unit earns after the assured period, from a real tenant, on the price you actually paid — that number is the truth.
Assured return vs pre-leased vs fresh commercial
There are three broad ways to earn from commercial property, and they are not equally safe.
A fresh, un-leased unit with an assured return is the riskiest: you are pre-paying for future income the developer promises to bridge, on an asset with no tenant yet. A fresh unit with no assured return is honest but demands that you underwrite the location and future demand yourself. A pre-leased (rented) unit — where a tenant is already in place on a registered lease — is generally the most reliable income, because the rent is real, the tenant's covenant is verifiable, and the yield (often a genuine 6–8%) is what it says it is. For most conservative investors, a pre-leased unit from a reputable developer at 6–8% is a better asset than a headline 15% assured-return promise on an unbuilt shop. Lower stated number, far higher certainty.
How commercial returns actually come
Strip away the marketing and commercial property earns in two ways: rent while you hold it, and capital gain when you sell. Both are driven by fundamentals that have nothing to do with a promised percentage.
Rent depends on footfall and occupier demand — a shop thrives only where enough of the right customers pass by, and an office leases only where businesses actually want to sit. It depends on the exact unit: ground-floor frontage near the main entrance performs; an upper-floor unit down a dead corridor can stay empty for years in the same project. And it depends on the tenant you secure and the lease terms. Capital value then follows from the same drivers plus the location's broader trajectory. This is why commercial demands far more selectivity than residential: within one project, two units at the same rate can have completely different outcomes.
The main commercial formats in NCR
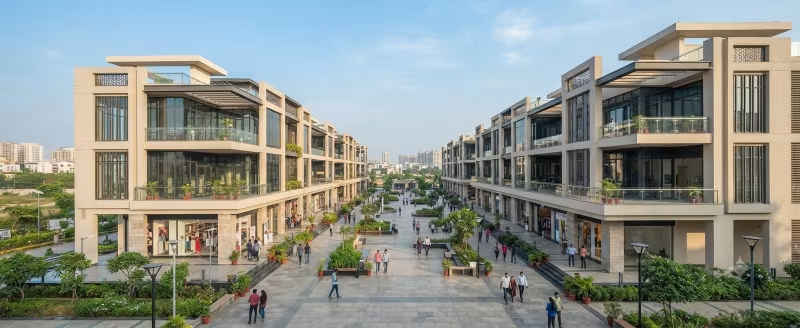
High-street retail — a linear row of shops within or beside a dense residential catchment. It works on captive local footfall; the risk is unit position and the catchment's actual spending. Our listing for Gaur World SmartStreet in Greater Noida West is an example of this format.
Mall and mixed retail-office hubs — organised, managed centres that can anchor larger tenants. Here your unit's fortune is tied to the whole centre's management and tenant mix, as with Gaur City Center or the airport-adjacent Gaur Aero Mall.
Commercial plots and SCO — land or shop-cum-office formats you develop or lease yourself, such as Gaur Aerocity Yamuna; highest control, but no income until built and let.
Studios and serviced suites — small-ticket units sold on future rental demand near a catalyst, like Gaur Aero Suites near the Jewar airport, or mixed studio-retail formats such as DASNAC Yuva and ATS Bouquet. These are the formats most often wrapped in assured-return pitches, so scrutinise them hardest.
How to evaluate a commercial buy — the honest checklist
Judge any commercial unit on fundamentals, not the promised return:
- Developer strength. Can this builder actually complete and, if leasing, sustain any commitment? A commercial promise is only as good as the promisor.
- RERA status. Confirm the project's registration on the official portal; commercial projects are covered too. No registration is a hard stop.
- Location and catchment. Is there genuine, present or credibly imminent demand — residents, offices, travellers — for this specific use at this specific spot?
- The exact unit. Floor, frontage, visibility, access and the intended use-mix around it. In commercial, the unit is the investment, not the project average.
- Realistic economics. What rent would a real tenant actually pay, and what yield does that give on your all-in cost? If the honest number is 6% and you are promised 15%, the gap is your risk.
- The fine print of any assured return. Who pays, from what, for how long, what happens at the end, and what your recourse is if payments stop. Get it in the registered agreement, not a side letter.
- Costs and taxes. Commercial carries higher GST and stamp implications and a thinner, slower resale market than residential.
Commercial or residential — which belongs in your portfolio
Commercial and residential are different tools. Residential gives you a home you can live in, the deepest resale liquidity, the easiest financing and modest but dependable rent; its weakness is a low 2–3% yield. Commercial gives you a higher potential yield and a business-like asset, but demands far more expertise, carries higher entry and exit friction, leases to a narrower pool, and punishes a poor unit choice severely. As a rough rule, secure your primary residential base first, and treat commercial as a later, eyes-open diversification once you can afford to lock money into a less liquid asset and are willing to choose it on fundamentals rather than a promised percentage. A first-time buyer stretching their budget for a "12% assured" shop, with no residential anchor, is taking on exactly the wrong risk in the wrong order.
Where in NCR the commercial story is strongest
The credible commercial demand drivers today are the infrastructure-backed corridors: the Jewar airport zone and Yamuna Expressway, the Noida Expressway and central-Noida office belt, the dense Greater Noida West catchment, and the Dwarka Expressway on the Gurgaon side. These are where genuine occupier demand is most likely to materialise. But "strong corridor" is not the same as "any unit here will pay 15%." Even on the best corridor, the format, the specific unit and the developer decide the outcome. Use the corridor to narrow your search, then apply the checklist above to the individual unit.
Costs, taxes and verification for commercial
Commercial purchases carry their own cost profile. GST on under-construction commercial property is higher than the residential rate and is a real line item; stamp duty and registration apply as for any property, on the higher of circle and transaction value. Maintenance and common-area charges on commercial can be steep. And resale is slower and to a narrower pool of buyers than a residential flat. On verification, apply the same RERA discipline as for a home — confirm the registration on the official portal, check the promoter and sanctioned plan, read the declared timeline — and additionally scrutinise the lease (for pre-leased units) or the realistic leasing prospects (for fresh units). Never let an assured-return headline substitute for any of this.
Who should — and should not — buy commercial
Consider commercial if you already have a stable residential base, you understand you are buying a business-like asset that lives or dies on tenants and footfall, you can hold through leasing cycles, and you are choosing on fundamentals. A pre-leased unit or a well-located shop in a proven catchment can be a genuinely good income asset.
Avoid it, or tread very carefully, if you are being drawn in primarily by an assured-return number, you need certain income you cannot afford to lose, or you are treating an unbuilt studio near a not-yet-mature catalyst as a guaranteed 12% bond. That is not what it is.
The honest bottom line
Commercial property has a real place in a portfolio, and NCR's infrastructure corridors offer genuine opportunity. But the "assured return" is a marketing device, not a measure of quality — it is an unguaranteed developer promise, usually funded by an inflated price, that ends when real risk starts. Ignore the promised percentage and judge the asset: developer, RERA status, location, the exact unit, and the rent a real tenant would actually pay. A dependable 7% you can verify beats a promised 15% you cannot. As a RERA-registered channel partner, Chahat Homes shares unit-level guidance, verified RERA status and honest, fundamentals-first advice on commercial property across NCR — and we will tell you plainly when an assured-return pitch does not stack up. No pressure, and zero brokerage on primary transactions.
Frequently asked questions
Are assured-return commercial schemes safe? Treat them as risk, not reassurance. An assured return is an unguaranteed developer promise paid from its own cash flow, not protected by RERA, usually priced into an inflated cost, and typically ending at possession. Judge the underlying asset, not the promised percentage.
Why would a developer offer 12–15% returns? Because it is a cheap, fast way to raise money from buyers and a powerful sales hook. Often the "return" is simply your own overpayment handed back in instalments. A promise that high is a reason to look harder, not to relax.
Is a pre-leased commercial property better than an assured-return one? Usually yes for income certainty. A pre-leased unit earns real rent from a verifiable tenant on a registered lease, often a genuine 6–8%, which is more reliable than a headline assured-return pledge on an unbuilt unit.
What rental yield is realistic on NCR commercial property? Well-located, leased commercial commonly yields in the mid-single digits to around 8% gross, depending on location, tenant and format — materially higher than residential's 2–3%, but nowhere near a guaranteed 15%.
Does RERA protect my assured-return income? No. RERA covers the project's registration, disclosures and timeline, but the assured-return payout is a private contractual promise. If payments stop, your recourse is contractual and can be slow.
Which commercial format is least risky? Generally a pre-leased unit from a credible developer, or a well-positioned high-street shop in a dense, proven catchment. Fresh studios and units sold mainly on assured returns near not-yet-mature catalysts are the most speculative.
Where in NCR is commercial demand strongest? The infrastructure-backed corridors — the Jewar airport zone and Yamuna Expressway, the Noida Expressway and central Noida, Greater Noida West, and the Dwarka Expressway. But the specific unit and developer still decide the outcome.
How do I verify a commercial project? The same way as a home: confirm the RERA registration on the official portal, check the promoter and sanctioned plan and declared timeline, and additionally scrutinise the lease or realistic leasing prospects and the fine print of any assured-return clause. We help you run these checks.
Sources & references

Mentioned in this article
Related Projects

ATS Infrastructure
ATS Bouquet
Sector 132, Noida

DASNAC
DASNAC Yuva
Sector 124, Noida

Gaurs
Gaur World SmartStreet
Greater Noida West, Noida
Keep reading
Related Insights

Investment Guide
New Gurgaon (Sectors 76–95): An Honest 2026 Value Investment Guide
An honest 2026 guide to investing in New Gurgaon (Sectors 76–95) — real prices, the metro and toll caveats, floors vs ap…

Investment Guide
Jewar Airport & Yamuna Expressway Property: An Honest 2026 Investment Guide
An honest, RERA-first guide to buying property near Jewar airport on the Yamuna Expressway in 2026 — real price trends,…
Investment Guide
Penthouses in Gurgaon: How Terrace Charging Actually Works
Why penthouse pricing cannot be compared on rate per sq.ft., how the three terrace-charging conventions work, and the qu…